LocalCircles estimates a 10% fall in UPI transaction value and a 4% fall in UPI transaction volumes post introduction of 0.4% MDR
- ● Only 14% of UPI users surveyed will continue using UPI for payments above INR 2,000 if the merchant passes on the MDR fee; 76% expect to use cards, cash or bank transfers most often
- ● Only 17% of merchants surveyed by LocalCircles are willing to bear the 0.4% MDR on UPI payments above INR 2,000; 41% will not bear any MDR
- ● LocalCircles surveys received over 67,000 responses from UPI users in 291 districts and over 32,000 responses from merchants in 242 districts
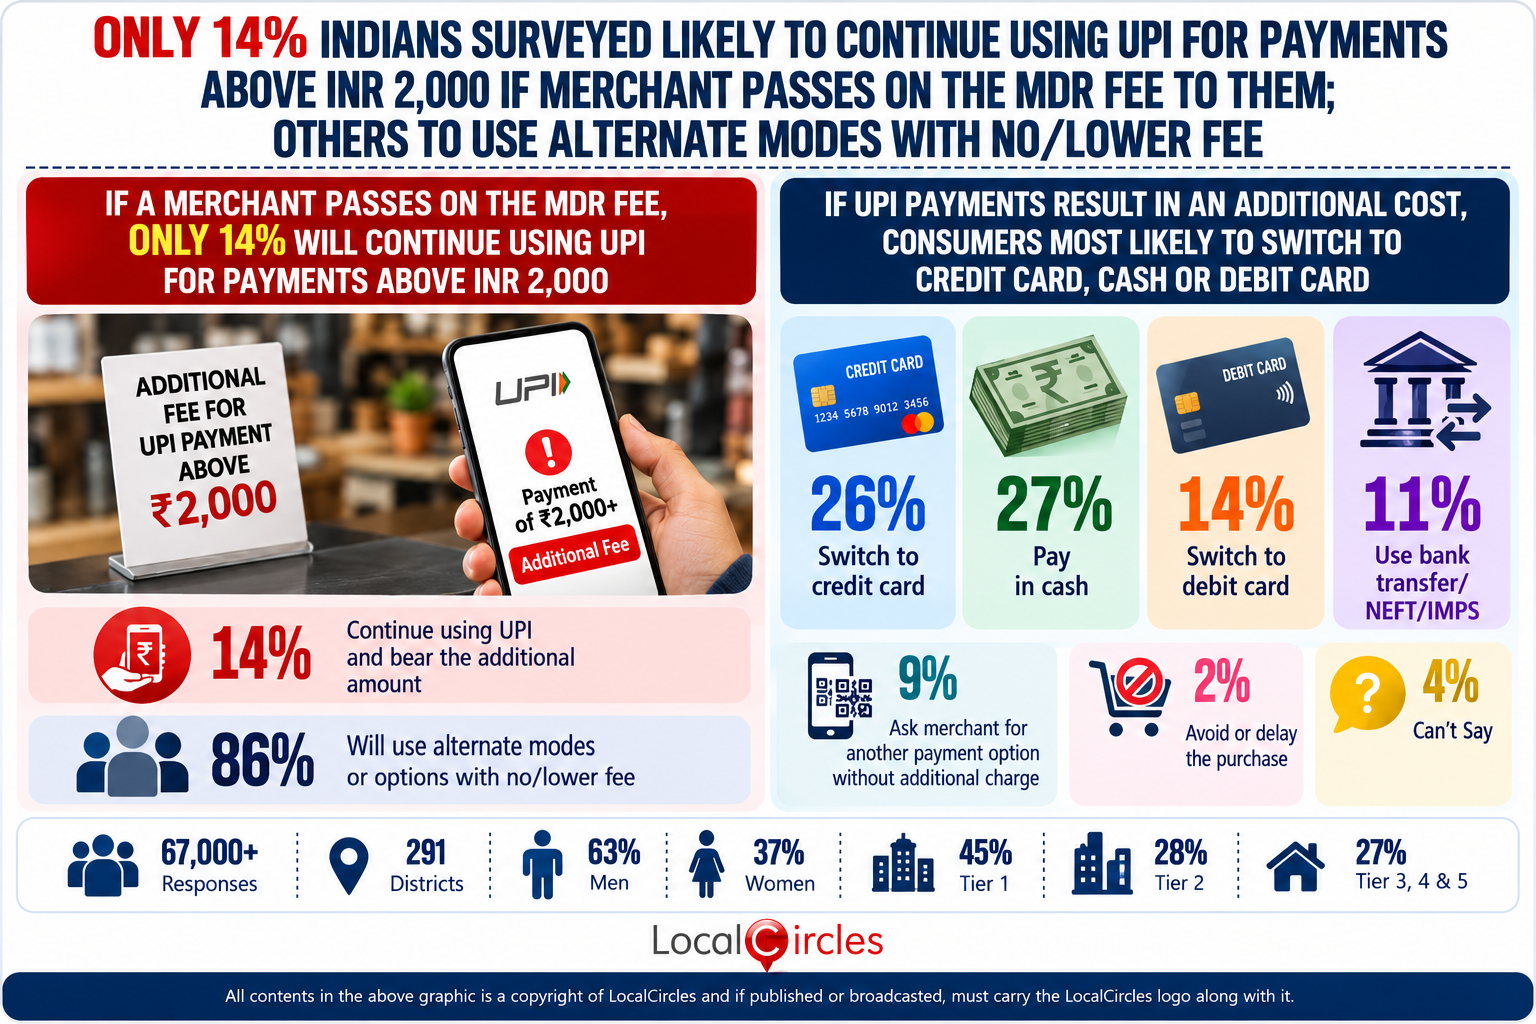
October 04, 2026, New Delhi: From October 15, 2026, paying by UPI at a shop will no longer be free for every merchant. A merchant discount rate (MDR) of 0.4% will apply to person-to-merchant (P2M) UPI payments above INR 2,000, ending more than six and a half years of zero MDR on UPI. The question now is who will bear this cost at the counter. LocalCircles surveys of both sides of the counter show that neither merchants nor consumers are ready to absorb it. Only 17% of merchants surveyed are willing to bear a 0.4% MDR, and only 14% of UPI users surveyed will keep paying by UPI if the fee is passed on to them. Based on these findings and NPCI data, LocalCircles estimates that UPI transaction value could fall by 10% and transaction volumes by 4% once the MDR goes live.
The change was set in motion on September 14, 2026, when the Ministry of Finance issued gazette notification S.O. 5067(E). It lists the payment modes that remain protected from charges: RuPay debit cards and UPI payments of up to INR 2,000. A day later, a Press Information Bureau (PIB) release and an NPCI circular set out the rates decided by the NPCI-chaired UPI and Services Steering Committee.
Under the framework, the MDR is capped at INR 300 per transaction for payments of INR 75,000 and above. Essential sectors such as railways, telecom, insurance, fuel and farm inputs pay a flat INR 5 per transaction, and capital market payments attract 0.02%. Person-to-person transfers remain free, and small merchants receiving up to INR 1 lakh a month through UPI QR codes are exempt. The government says around 96% of merchant transactions will not be affected.
The legal basis was laid in August 2026, when Parliament amended Section 10A of the Payment and Settlement Systems Act, 2007, through the Taxation and Other Laws (Amendment) Bill, 2026. The amendment removed the blanket ban on charges for RuPay debit card and UPI payments that had been in place since January 2020, and now lets the Centre notify which payment modes stay free. The Bill received presidential assent on August 17, 2026.
The government has made it clear that consumers are not the target. The Ministry of Finance has said MDR "is neither a tax nor a charge collected by Government or NPCI"; it is shared among banks, payment service providers and UPI apps to run and expand the network. Banks have been directed to ensure that merchants do not pass the charge on to customers, and UPI apps are barred from levying platform fees or hidden charges. On September 22, Finance Minister Nirmala Sitharaman said "the responsibility does not lie with the customer". Finance ministry officials will monitor daily from October 15 whether merchants are passing on the MDR, and the Ministry is working with the Indian Banks' Association (IBA) on a mechanism for banks to monitor merchants. The IBA will also run an awareness campaign in regional languages to tell consumers they are not required to pay any extra charge on UPI.
Beyond monitoring, however, the framework does not yet spell out penalties or a refund route for a consumer who is wrongly charged. That gap matters. For years, schools, ticketing portals, utility billers and fuel outlets have added card costs to bills as a "convenience fee" or "service charge". At 0.4%, a merchant pays INR 20 on a INR 5,000 sale and INR 200 on a INR 50,000 sale. An 18% GST is also levied on the MDR, though merchants can claim input tax credit, and government sources have said the matter will be placed before the GST Council. Many merchants will be tempted to recover the cost from their customers.
The case for the MDR rests on the cost of running the network. Government incentives for UPI peaked at INR 3,631 crore in FY2023-24, but only INR 2,000 crore has been allocated for FY2026-27. The Department of Financial Services has told a parliamentary panel that zero MDR was "financially unsustainable in the long run", and industry bodies such as the Payments Council of India have long argued for an MDR on large merchants. The stakes are high. UPI processed a record 24.51 billion transactions worth INR 29.82 lakh crore in August 2026. Of these, 15.51 billion were merchant payments worth INR 8.95 lakh crore, and payments above INR 2,000 made up 67% of that merchant value. The MDR will therefore fall on a small share of transactions that carry most of the money.
Trader bodies have pushed back. The Confederation of All India Traders (CAIT) has warned that retailers may split bills, shift to bank transfers or quietly reprice goods. The Retailers Association of India has said the burden could undo years of progress. In Bengaluru, traders have warned of a return to cash, with the FKCCI saying even a small cost "may discourage digital payments". The Chamber of Trade and Industry (CTI) has sought a rollback, saying the MDR will affect around 6 crore traders. CAIT president Praveen Khandelwal has sought a brief deferral of the rollout for a nationwide awareness drive, and has suggested that customers use RuPay debit cards, which carry no MDR, for higher-value payments. On September 30, a CAIT-led delegation of about 20 trade leaders met the Finance Minister, who assured them that their concerns would receive due consideration. Trade bodies then withdrew a "No UPI Day" protest planned for October 2. The 0.4% MDR, however, remains set to take effect on October 15.
Consumers have long been sensitive to any charge on UPI. In an August 2026 LocalCircles survey of over 45,000 UPI users across 322 districts, 53% said they would move away from UPI for larger payments if the MDR was recovered from them. In an earlier survey released in March 2025, 73% of UPI users said there should be no charge on UPI transactions at all.
With the rollout two weeks away and pass-through the biggest open risk, LocalCircles asked consumers what they would do if a merchant added the fee to their bill. This survey received over 67,000 responses from UPI users located across 291 districts of India. Its findings are presented below, alongside those of the LocalCircles merchant survey released on September 16, 2026, which received over 32,000 responses from businesses across 242 districts.
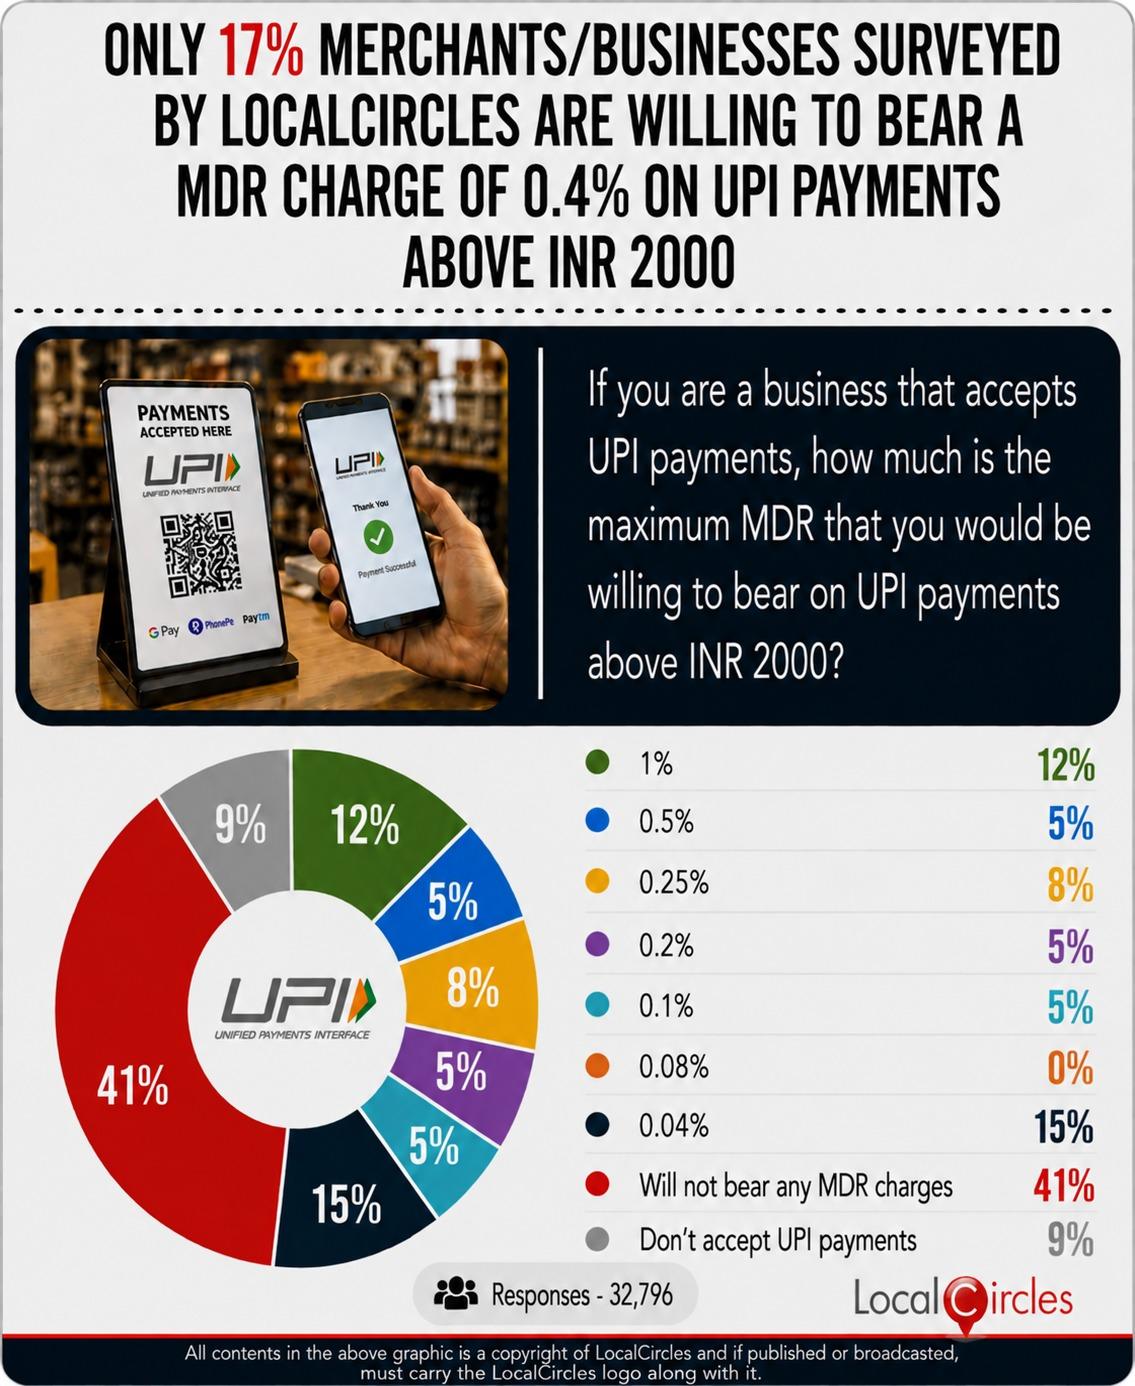
If a merchant passes on the MDR fee, only 14% of UPI users surveyed will continue paying by UPI for purchases above INR 2,000
The survey asked UPI users, "If a merchant asks you to pay an additional amount/fee for making a UPI payment above INR 2,000, what would you most likely do?" This question received 31,206 responses.
In response, 27% said they would "pay in cash" and 26% said they would "switch to credit card". 14% would "switch to debit card" and 4% would "use bank transfer/NEFT/IMPS". 9% would "ask the merchant for another payment option without an additional charge" and 2% would "avoid/delay the purchase". Only 14% said they would "continue paying by UPI and bear the additional amount", while 4% could not say.
Put simply, only 1 in 7 UPI users surveyed will pay the fee. Over 8 in 10 will move to another mode or option with no or lower cost, and the single largest group, at 27%, will go back to cash.
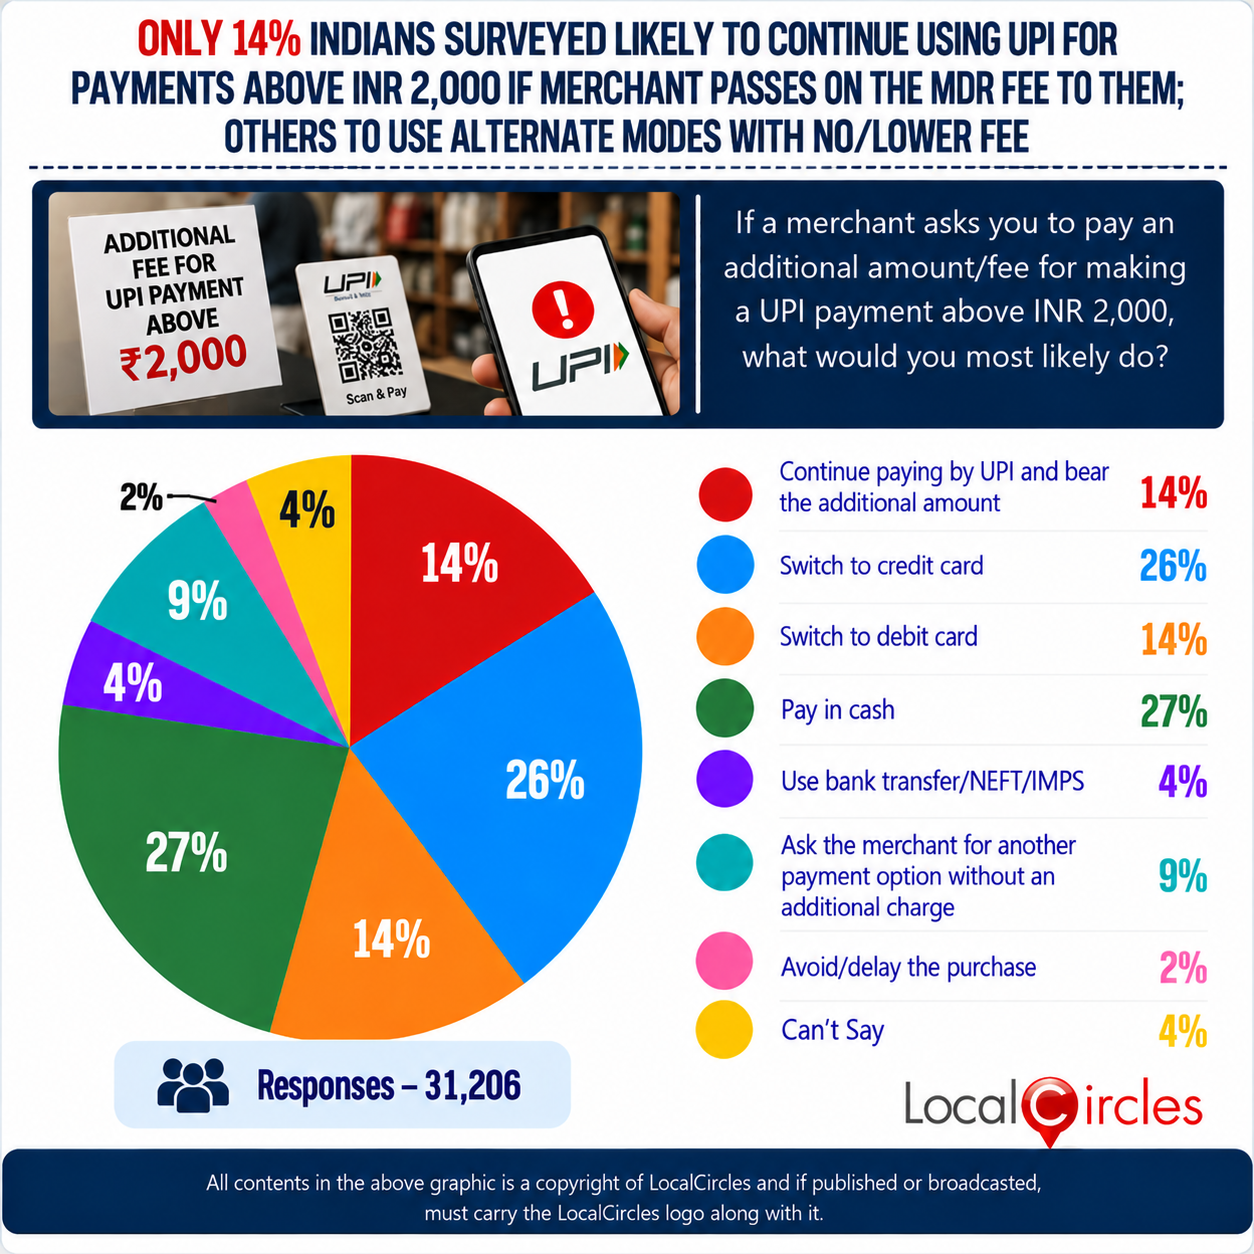
If UPI carries an additional cost, 76% of UPI users surveyed expect to use cards, cash or bank transfers most often for purchases above INR 2,000
To understand the lasting impact on payment habits, the survey asked, "Going forward, for purchases above INR 2,000, which payment mode do you expect to use most often if UPI payments result in an additional cost?" This question received 37,654 responses.
In response, 26% said "credit card" and another 26% said "cash". 13% said "debit card" and 11% said "bank transfer/NEFT/IMPS". Only 20% said they would still use "UPI" most often, while 4% could not say. None chose any other digital payment method.
This means 76% of UPI users surveyed expect to move their larger payments off UPI if it carries an extra cost. Cards together would take 39%, and cash would regain about a quarter of these payments. This is the high-value segment that carries most of the value on UPI today.
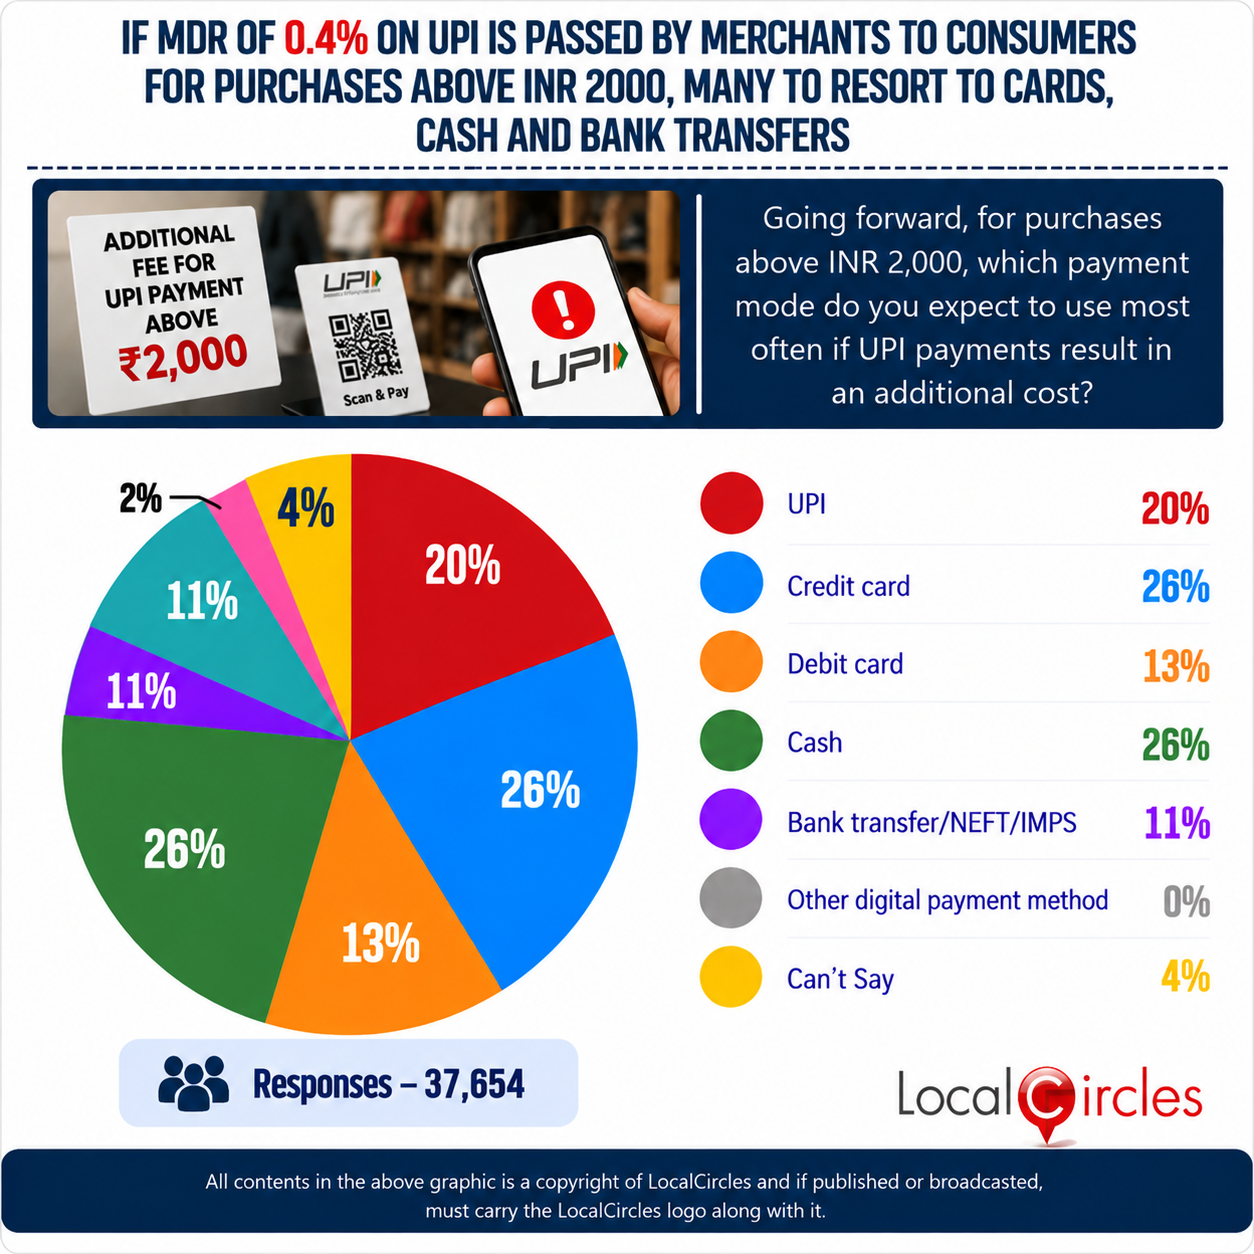
Only 17% of merchants surveyed are willing to bear a 0.4% MDR on UPI payments above INR 2,000; 41% will not bear any MDR
The merchant survey asked businesses, "If you are a business that accepts UPI payments, how much is the maximum MDR that you would be willing to bear on UPI payments above INR 2000?" This question received 32,796 responses.
In response, 41% said they "will not bear any MDR charges" and 9% said they "don't accept UPI payments". Among the rest, 15% would bear a maximum MDR of 0.04%, the nominal rate many merchants had hoped for. 5% each would bear up to 0.1%, 0.2% and 0.5%, 8% up to 0.25% and 12% up to 1%. None chose 0.08%.
Taken together, half the merchants surveyed would bear a nominal MDR of 0.04%, but the share falls sharply as the rate rises. 35% would bear 0.1% or more, 25% would bear 0.25% or more, and only 17% would bear 0.4% or more. At the rate now notified, 83% of merchants surveyed are not willing to absorb the charge. These are the merchants most likely to pass it on to customers, or to steer them towards cash and other modes.
LocalCircles estimates a 10% fall in UPI transaction value and a 4% fall in UPI transaction volumes post introduction of 0.4% MDR
Reading the consumer and merchant surveys together with NPCI data, LocalCircles estimates that UPI transaction value will fall by about 10% and UPI transaction volumes by about 4% once the 0.4% MDR comes into effect. The estimate rests on three factors: where the MDR applies, who is likely to bear it, and how consumers will respond if it reaches them.
Where the MDR applies: The MDR falls on a narrow slice of UPI that carries a large share of the money. P2M payments above INR 2,000 make up less than 5% of merchant transactions by volume (about 4% in August 2026), but about 67% of merchant payment value, or roughly INR 6 lakh crore a month. That is about one-fifth of all UPI value.
Who bears the cost: With 83% of merchants surveyed unwilling to absorb a 0.4% MDR, most merchants above the INR 1 lakh a month exemption threshold are likely to try to recover it, openly as a surcharge or through pricing, or to steer customers towards cash, bank transfers or cards. If the charge reaches consumers, 86% of UPI users surveyed will use another mode or option, and 76% expect to use another mode most often for such purchases.
Impact on value (10%): Government estimates indicate that about 80% of UPI payments above INR 2,000 are made to large corporate merchants. Factoring this in, along with the merchants willing to absorb the MDR, the consumers willing to pay the fee, and the friction of switching payment modes immediately, LocalCircles estimates that UPI transaction value is likely to fall by 10% in the first full month after the 0.4% MDR goes live.
Impact on volume (4%): With less than 5% of UPI merchant transactions above INR 2,000, the fall in volumes will come from two sources. The first is the direct loss of transactions of INR 2,000 or more at MSME merchants, which LocalCircles estimates at about 1% of UPI volumes. The second, and larger, is a network effect: consumers who stop using UPI for high-value purchases at an MSME merchant are likely to stop using UPI with that merchant altogether, which LocalCircles estimates will take away another 3%. Together, these two factors lead to an estimated 4% fall in UPI transaction volumes.
In summary, the findings from both sides of the counter point the same way. Only 17% of merchants surveyed are willing to bear a 0.4% MDR on UPI payments above INR 2,000, and 41% will not bear any MDR at all. If merchants pass the fee on, only 14% of UPI users surveyed will continue paying by UPI; 27% will pay in cash, 26% will switch to a credit card and 14% to a debit card. Going forward, 76% expect to use cards, cash or bank transfers most often for such purchases if UPI costs extra.
In other words, if the charge reaches the customer, the transaction is likely to leave UPI. LocalCircles estimates that this will lead to a 10% fall in UPI transaction value and a 4% fall in UPI transaction volumes after the 0.4% MDR comes into effect. With cash the single largest alternative, the shift would also reverse some of the formalisation gains of the last decade.
One of the considerations for the Government could be to go live with MDR fee of 0.4% for transactions above INR 2000 for just large corporate merchants and leave the MSME merchants out of the ambit of MDR. LocalCircles estimates that Such a move would help the Government still generate 98% of the MDR fee while avoiding the disruption in the last mile.
LocalCircles will be escalating these findings to the Department of Financial Services, the Reserve Bank of India and NPCI ahead of the October 15 rollout.
UPI grew because it was free for both the payer and the shop. Keeping it free for the consumer and the MSME merchant ensures that disruption is minimal while a beginning is made to levy MDR on large corporate merchants. Basis the findings from this phase of the MDR levy, a more acceptable plan could be formulated for levying MDR on the MSME merchants.
Survey Demographics
Consumer Survey: The survey received over 67,000 responses from UPI users located across 291 districts of India. 63% of respondents were men and 37% were women. 45% of respondents were from tier 1, 28% from tier 2 and 27% from tier 3, 4 & 5 districts.
Merchant Survey: The survey received over 32,000 responses from businesses/merchants located across 242 districts of India. 48% of respondents were from tier 1, 33% from tier 2 and 19% from tier 3 & 4 districts. Both surveys were conducted via the LocalCircles platform, and all participants were validated citizens who had to be registered with LocalCircles to participate.
About LocalCircles
LocalCircles, India’s leading Community Social Media platform enables citizens and small businesses to escalate issues for policy and enforcement interventions and enables Government to make policies that are citizen and small business centric. LocalCircles is also India’s # 1 pollster on issues of governance, public and consumer interest. More about LocalCircles can be found on https://www.localcircles.com
For more queries - media@localcircles.com, +91-8585909866
All content in this report is a copyright of LocalCircles. Any reproduction or redistribution of the graphics or the data therein requires the LocalCircles logo to be carried along with it. In case any violation is observed LocalCircles reserves the right to take legal action.
Enter your email & mobile number and we will send you the instructions.
Note - The email can sometime gets delivered to the spam folder, so the instruction will be send to your mobile as well


